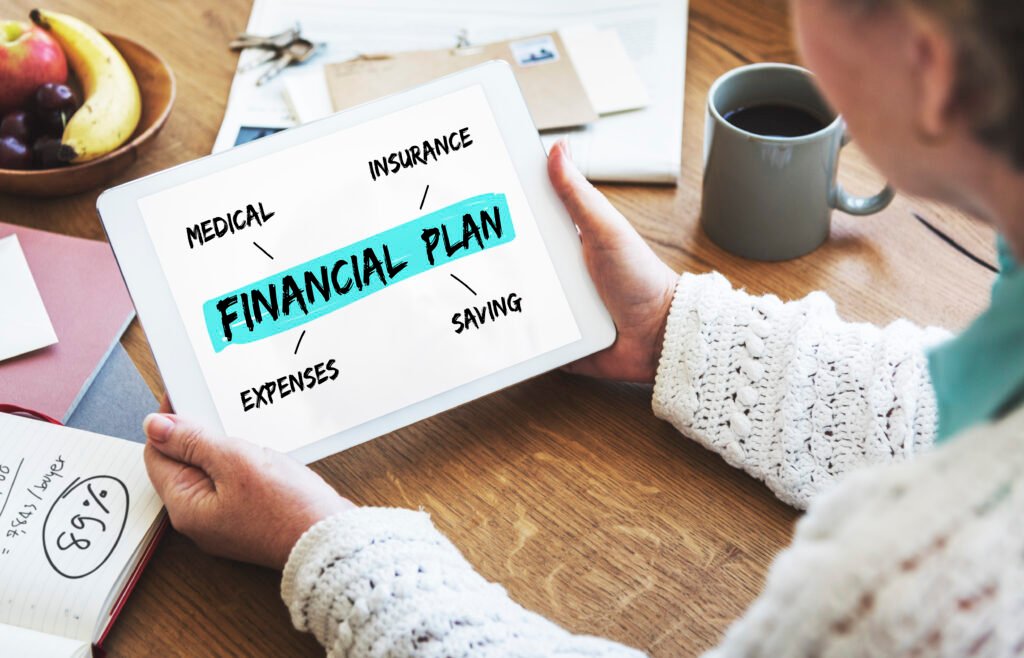
Financial Plan Retirement Investment Diagram Concept
A retirement planning advisor in Downers Grove, IL can help individuals prepare for retirement by bringing together investment management, retirement income planning, tax planning, risk assessment, insurance needs, and estate or legacy goals.
The advisor can review a person’s current financial position, identify potential gaps, and help create a strategy for using and protecting assets throughout retirement. For small business owners, retirement planning can also include reviewing employer retirement plans and coordinating business and personal financial goals.
Building a Strong Retirement Strategy
A retirement strategy should be based on more than an account balance. It should consider how much a person may need, how investments fit into the plan, and what risks could affect financial security.
A retirement planning process may include:
- Income planning: Identifying potential income sources and considering how they may work together.
- Investment management: Reviewing investments based on retirement goals, time horizon, and risk considerations.
- Risk assessment: Looking at financial risks that could affect savings and future income.
- Insurance needs: Reviewing life, disability, and long-term care coverage as part of a broader financial plan.
- Tax planning: Considering how taxes may affect retirement income, withdrawals, and investment decisions.
- Healthcare planning: Accounting for healthcare-related expenses that may arise during retirement.
- Long-term planning: Connecting current financial decisions with future family and estate goals.
This type of planning can be especially useful when someone is nearing retirement and has several accounts, investments, insurance policies, or income sources that need to work together.
Retirement Planning for Small Business Owners
Small business owners often have retirement planning needs that differ from employees. They may need to think about their personal retirement while also providing benefits for employees and managing business cash flow.
A small business 401(k) plan design can help establish a retirement program that fits the needs of the business and its workforce. Plan design may involve reviewing contribution structures, eligibility rules, investment choices, and other plan features.
Business owners should also consider how a retirement plan fits into the larger financial picture.
Important areas may include:
- Business cash flow and available contributions
- Owner and employee retirement goals
- Tax considerations
- Employee participation
- Investment options
- Future business plans
- Coordination between business and personal retirement savings
The right structure depends on the business, its employees, financial goals, and other circumstances. Professional guidance can help business owners understand these moving parts before choosing a retirement strategy.
Retirement planning also involves decisions that may happen years before the actual retirement date. Reviewing savings rates, investments, insurance coverage, and expected income early can give people more time to adjust their strategy when needed.
Connecting Retirement with Wealth Planning
Retirement planning does not end when someone leaves the workforce. Financial needs can continue to change throughout retirement. Investment withdrawals, tax decisions, healthcare expenses, family support, charitable giving, and changes in spending can all affect a long-term plan. Small business owners also have another layer to consider. Their business may be one of their largest assets, making business succession and retirement planning closely connected.
A small business owner retirement plan options review can help compare available approaches based on factors such as business size, employee needs, contribution goals, tax considerations, and administrative requirements. There is no single retirement plan that works for every business, so comparing the available structures is an important part of the process.
Planning for Family and Legacy Goals
For many people, retirement planning is also about what happens to their wealth after their lifetime. Estate and legacy planning can help families organize how assets may be transferred and identify the people or causes they want to support.
A legacy planning advisor in DuPage County can help families think through goals such as wealth transfer, charitable giving, beneficiary arrangements, and the role of different assets in an estate plan. This work can complement retirement and investment planning by considering both present financial needs and future family priorities.
Legacy planning may involve:
- Reviewing beneficiaries on financial accounts
- Coordinating retirement assets with an estate plan
- Considering gifts to family members
- Planning for charitable intentions
- Reviewing insurance as part of wealth transfer
- Organizing financial documents and important information
- Working with attorneys and tax professionals when specialized advice is needed
Good planning should also be reviewed as life changes. Marriage, divorce, a new business, the birth of a grandchild, a major inheritance, or a change in retirement timing can all affect financial priorities.
Making Retirement Decisions with Greater Clarity
Retirement planning works best when it reflects the whole financial picture. Investments,
Taxes, insurance, retirement accounts, business interests, and family goals can influence one another. Looking at these areas together can make it easier to identify gaps and understand the potential impact of major financial decisions.
People nearing retirement can benefit from starting with a clear review of their current position. This can include listing assets and debts, identifying expected income, reviewing investments, estimating future expenses, and identifying important family or legacy goals.
From there, a financial strategy can be adjusted as circumstances change. Regular reviews can help keep the plan aligned with changing income needs, market conditions, tax considerations, and personal priorities.
Final Thoughts
Retirement planning is more than preparing a savings account for the future. It is a process of coordinating income, investments, risk, taxes, insurance, and family goals into a practical financial strategy. For individuals, families, and business owners in the Downers Grove area, understanding these connections can provide a clearer framework for preparing for retirement and protecting long-term financial goals.