Introduction
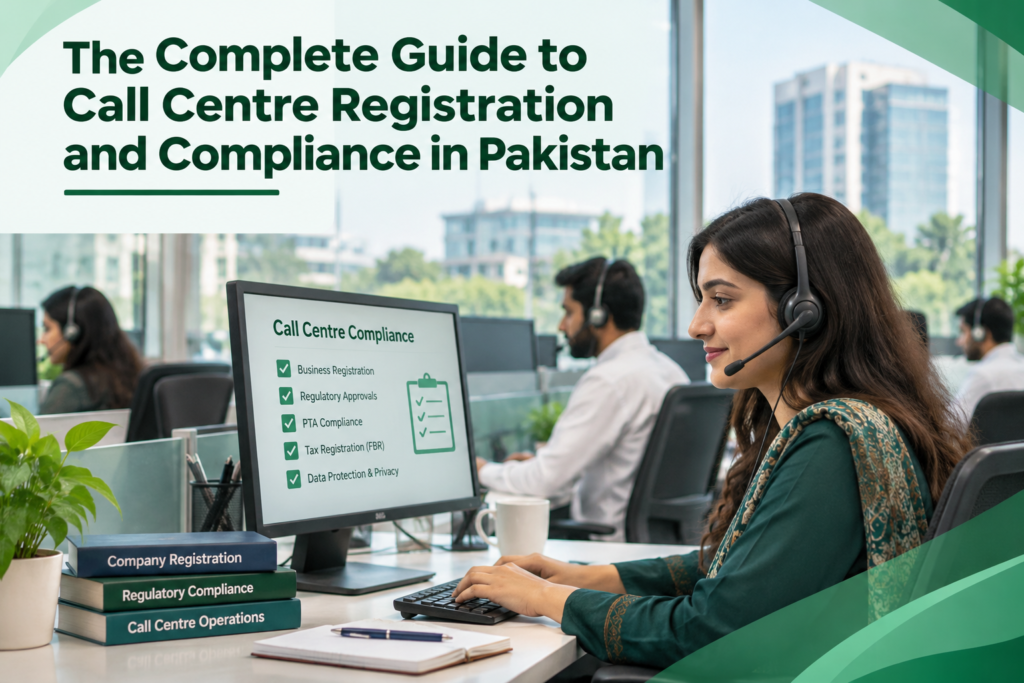
Pakistan’s call centre industry serves local and international clients. Owners must select a legal structure, complete registrations, manage staff, and understand tax obligations. This guide covers call centre registration in Pakistan, compliance duties, and WHT rates call centre operators should understand for Tax Year 2027.
1. Select a Business Structure
Choose a sole proprietorship, partnership or association of persons, or company. Consider ownership, liability, investment, client expectations, and expansion. A company has a separate legal identity and may suit larger contracts, corporate banking, or investors.
For a company, complete SECP company incorporation under the Companies Act, 2017 by reserving a name, submitting incorporation details and required documents, and paying the prescribed fee. Sole proprietors and partnerships follow different routes. Not every call centre needs to become a private limited company.
2. Obtain NTN and Complete FBR Registration
Obtain the appropriate National Tax Number (NTN) and access to FBR IRIS registration. Keep business, ownership, address, and bank details consistent. Understand annual return and withholding deposit or statement duties, secure portal credentials, and assign filing responsibility.
3. Apply for PSEB Registration
The Pakistan Software Export Board supports Pakistan’s IT and IT-enabled services sector. The Income Tax Ordinance includes inbound and outbound call centres within IT-enabled services. For exporters, PSEB registration for call centres is important because reduced withholding treatment depends on registration and certification conditions.
Prepare business registration documents, NTN and bank details, office address evidence, contact information, and a service description. Check the current PSEB portal for its checklist, fees, branch requirements, and renewal rules. Keep the certificate active and update ownership, address, branch, or service changes.
4. Understand WHT Rates for Call Centres
The withholding rate depends on income type, payment route, taxpayer status, and the relevant provision of the Income Tax Ordinance.
For Tax Year 2027 (1 July 2026 to 30 June 2027), the FBR rate card sets a 0.25% withholding tax rate on qualifying export proceeds from software, IT services, or IT-enabled services when the exporter is PSEB-registered and meets Section 154A conditions. The statutory definition includes inbound and outbound call centres.
Other export-service cases under Section 154A generally carry 1% of proceeds. A call centre cannot claim the reduced rate based on its name alone; services, registration, invoices, and bank records must support eligibility.
For illustration, on qualifying export proceeds equivalent to Rs. 1,000,000, a 0.25% deduction equals Rs. 2,500. At 1%, it equals Rs. 10,000. Actual tax treatment depends on the transaction and statutory conditions.
These are export rates, not universal rates for domestic contracts, salaries, rent, or supplier invoices. Domestic services may fall under Section 153 and salaries under Section 149. Check the current rate card for each transaction.
Under Section 154A, the authorized foreign-exchange dealer deducts tax when export proceeds are realized. Final-tax treatment is subject to statutory conditions. Keep remittance evidence, invoices, contracts, bank advice, and deduction certificates.
5. Maintain Payroll and Salary Tax Compliance
Payroll may include salaries, commissions, attendance incentives, overtime, night allowances, bonuses, and deductions. Apply salary tax where required and maintain appointment letters, attendance, payslips, salary transfers, and deduction calculations. Strong call centre payroll compliance reduces disputes.
6. Register Eligible Employees for EOBI
Employee benefits are a key part of call centre compliance in Pakistan. Assess coverage under the Employees’ Old-Age Benefits Institution and the relevant provincial social security system. Applicability depends on employee coverage rules, the establishment, wage base, and governing legislation.
Register eligible employees, calculate and pay contributions on time, and retain identification, joining dates, salary details, and payment evidence.
7. Maintain Corporate and Provincial Filings
An incorporated call centre must meet continuing obligations after incorporation. Maintain statutory registers, minutes, accounting records, and updated director and shareholder information. File annual returns and event-based forms when required, and prepare accounts and meetings under applicable company law.
Check whether provincial sales tax registration and returns apply. The authority depends on the business location and service type; overseas clients do not automatically remove filing duties.
8. Use Authorized Telecom Services and Protect Data
Reliable voice connectivity is essential. Obtain telecom and VoIP services through appropriately authorized providers and check applicable PTA requirements, approvals, or whitelisting arrangements. PSEB’s public updates highlight training, certifications, and facilitation of compliant VoIP approvals.
Protect customer information with restricted access, secure devices, staff training, and clear data-handling rules. Review contracts for confidentiality, call recording, and retention.
9. Create a Compliance Calendar
Assign responsibility for income tax returns, withholding statements, tax deposits, payroll, EOBI contributions, provincial filings, PSEB renewal, and SECP submissions. Reconcile bank receipts and deductions monthly instead of waiting until year-end.
Review compliance each month: confirm registrations are active, match foreign receipts with invoices and bank advice, compare tax deducted with the applicable rate, and check payroll totals against salary records. Escalate missing documents or unusual deductions promptly. This routine helps management spot errors before deadlines and audits consistently, strengthening accountability across the team over time.
Common Mistakes to Avoid
Common problems include incomplete registration, expired PSEB status, confusion between export and domestic revenue, outdated rates, missed employee registrations, and unreconciled bank deductions. Verify social media claims against official rules for the relevant tax year.
Conclusion
Successful call centres manage registration, tax, payroll, employee benefits, corporate filings, and telecommunications together. This protects cash flow and builds client confidence. Pakistan’s First Online Consultants (PFOC) supports businesses with registration, tax, payroll, and compliance services. Review your obligations as your business expands or changes.
Frequently Asked Questions
What registrations does a call centre need in Pakistan?
Requirements depend on structure and services. Common steps include business registration, NTN and FBR setup, relevant PSEB registration, employee registrations, and applicable provincial or telecom approvals.
What are the WHT rates call centre exporters should know for Tax Year 2027?
Qualifying PSEB-registered IT-enabled service exporters may qualify for the 0.25% Section 154A rate. Other export-service cases generally carry 1%. Confirm eligibility before applying a rate.
Is PSEB registration important?
Yes. It supports recognition as an IT-enabled service provider and is relevant to reduced export withholding tax treatment where statutory conditions are met.